Tag: Retail

  • Our real time case study-When E-commerce Orders Were Failing, the Problem Was Inside the Stores

    Our real time case study-When E-commerce Orders Were Failing, the Problem Was Inside the Stores

    An international retail client came to us with a simple but serious problem:

    Their e-commerce business was growing, but they were not able to fulfil around 30% of the orders.

    The business had around 400 hypermarkets and supermarkets across the country.

    Customers could place orders through the company’s own e-commerce website as well as through other marketplace platforms.

    The stores were connected to these platforms and were expected to fulfil customer orders from their existing inventory.

    On paper, the model looked simple.

    In reality, it was creating a major operational problem.

    The same inventory was serving two customers:

    the customer standing inside the store and the customer ordering online.

    And the fulfilment rate was only around 70%.

    That meant roughly 3 out of every 10 orders were facing a fulfilment problem.

    The first question was not:

    “How do we increase inventory?”

    The first question was:

    “Where exactly is the problem happening?”

    We started with the data.

    We looked at four areas.

    1. Order fulfilment lead time

    We studied how much time the stores actually had to pick and service an online order.

    2. Demand forecast

    We checked the demand quantity being generated by the application and whether it reflected actual store-level demand.

    3. Inventory update frequency

    We examined the time gap between the physical inventory available in the store and the inventory quantity visible on the e-commerce platform.

    4. Store-level fulfilment

    We mapped which stores were servicing which platforms and where orders were getting missed.

    That analysis started showing us something important.

    The problem was not simply a lack of inventory.

    The bigger problem was inventory visibility and inventory accuracy.

    Different platforms were generating orders at different times.

    The company’s own website was generating orders.

    Customers were simultaneously buying from the physical stores.

    The store inventory was changing continuously.

    But the e-commerce platforms were not receiving inventory updates quickly enough.

    So the system could show a product as available online even when the store could no longer fulfil the order.

    That created an out-of-stock situation after the customer had already placed the order.

    Then we applied Pareto.

    We analysed the SKU-level data.

    The result was clear.

    Around 60–70% of the fulfilment problem was concentrated in the top-selling SKUs.

    That changed our approach.

    We did not try to fix hundreds or thousands of SKUs at once.

    We went after the SKUs that were creating the biggest impact.

    We worked with the stores to identify and correct ambiguous inventory quantities.

    We looked at the actual stock on the ground.

    We compared it with the system stock.

    And we focused on improving the connection between the store inventory and the e-commerce platforms.

    One important recommendation was technology-related.

    The ideal solution was real-time inventory synchronisation.

    But implementing a completely real-time system would have required additional technology changes and investment.

    So we looked at what was commercially practical.

    Our recommendation was:

    If real-time synchronisation is not immediately possible, reduce the inventory update cycle to around 10 minutes.

    That small change could significantly reduce the gap between:

    Physical Stock → System Stock → Online Availability

    The technology alone, however, was not enough.

    We went to the stores.

    This is where Gemba became important.

    Data can tell you where the problem is.

    But going to the actual workplace helps you understand why it is happening.

    We checked what was happening at store level.

    We looked at the actual inventory.

    We understood how orders were coming from different platforms.

    We checked how the store teams were responding.

    We compared system inventory with physical inventory.

    And we connected those observations back to the data.

    That combination gave us a much clearer picture.

    Technology showed us the symptom.

    Data showed us the concentration.

    Pareto showed us where to focus.

    Gemba showed us the operational reason.

    The result?

    The out-of-stock problem reduced from around 30% to approximately 11%.

    That took the fulfilment rate from around:

    70% → 89%

    in a relatively short period.

    More importantly, the client did not need to simply keep adding inventory to solve the problem.

    We improved the way existing inventory was being seen, updated and allocated for e-commerce fulfilment.

    The client subsequently took the process forward and continued following the improvements internally.

    What did we actually change?

    It was not one big technology project.

    It was a combination of several practical interventions:

    • Analysed fulfilment lead time

    • Studied demand forecasting logic

    • Mapped inventory update frequency

    • Identified store-level fulfilment gaps

    • Created SKU-level Pareto analysis

    • Focused on high-impact SKUs

    • Checked physical inventory against system inventory

    • Identified ambiguous inventory quantities

    • Recommended faster inventory synchronisation

    • Recommended approximately 10-minute inventory updates where real-time integration was not immediately practical

    • Conducted Gemba-level validation

    • Connected technology data with store operations

    And that is what made the difference.

    The bigger lesson for retailers

    Many retailers assume that e-commerce fulfilment problems can be solved by:

    “Keep more stock.”

    I don’t agree.

    Sometimes the inventory is already sitting inside the store.

    The problem is that the system does not know the right quantity at the right time.

    And when that happens, the customer sees:

    “Available”

    places the order,

    and then receives:

    “Sorry, this item is unavailable.”

    That is not just an inventory problem.

    It is a technology + data + process + store execution problem.

    For retailers operating an omnichannel model, the real question is not simply:

    “How much inventory do we have?”

    It is:

    “Do we know exactly where that inventory is, whether it is actually available, and how quickly can we make that information visible to the customer?”

    That is where e-commerce, store operations, data analytics and Gemba have to work together.

    And sometimes, a relatively simple change in the way inventory is updated can create a much bigger impact than simply adding more stock.

    From 70% fulfilment to 89%.

    Not by throwing more inventory at the problem.

    By finding the real problem first.

  • Quick Commerce Is No Longer About 10-Minute Delivery — It Is Becoming a New Retail Format

    Quick Commerce Is No Longer About 10-Minute Delivery — It Is Becoming a New Retail Format

    When quick commerce started gaining traction in India, the big attraction was simple: get your order in 10 minutes.

    Milk, bread, eggs, snacks, cold drinks, fruits and vegetables — things people needed quickly could suddenly reach their homes without a trip to the neighbourhood store.

    For a while, the entire conversation was about speed.

    Who can deliver faster?

    10 minutes or 15 minutes?

    But I think we are now looking at something much bigger.

    Quick commerce is slowly becoming a new retail format.

    The reason is quite simple. These platforms are no longer trying to solve only an urgent shopping need. They are trying to become part of the customer’s regular shopping behaviour.

    Think about how people actually shop.

    They don’t always wake up thinking, “Today I will visit a grocery store.”

    They think, “We are out of milk.”

    “I need snacks for tonight.”

    “I forgot toothpaste.”

    “Guests are coming.”

    “I need a small gift.”

    These are shopping missions.

    Quick commerce is trying to capture these missions one by one.

    And that changes the game.

    The first generation of quick commerce was largely about groceries and everyday essentials. Today, the assortment is moving into many other categories — beauty, personal care, electronics, gifting, home products and more.

    Once the customer starts buying these categories regularly, the platform is no longer just delivering products.

    It is competing for the customer's basket.

    That is where I believe traditional retailers need to pay attention.

    Because the biggest change is not happening in delivery.

    It is happening in inventory.

    A 10-minute delivery promise sounds impressive to the customer. But behind that promise sits a much more complicated operation.

    The product has to be available close to the customer.

    The forecast has to be reasonably accurate.

    The right quantity has to be stocked.

    The order has to be picked quickly.

    The product has to be packed correctly.

    And someone still has to deliver it profitably.

    If the retailer keeps too little stock, the customer sees “out of stock.”

    Keep too much stock and the business starts carrying unnecessary working capital. Products age. Discounts increase. Fresh products get damaged. Wastage goes up.

    This becomes particularly important in fruits and vegetables and other perishables.

    A retailer cannot solve an availability problem simply by putting more stock into a dark store.

    The quality of the forecast matters.

    This is something I have seen repeatedly in retail. Inventory problems are often treated as a technology problem. In reality, the technology can only work as well as the demand data, processes and discipline behind it.

    That is why I think the next competitive battle in quick commerce will not simply be about who delivers in 10 minutes.

    It will be about who can maintain better availability without carrying excessive inventory.

    That is a very different game.

    Traditional retailers already understand many parts of this equation.

    They have spent decades managing assortment, inventory, margins, store productivity, shrinkage, wastage and working capital.

    What is changing is the operating model.

    A traditional store waits for the customer to walk in.

    A dark store waits for the order to come through the app.

    The traditional store uses shelves to present products.

    The quick-commerce platform uses the app to present products.

    The traditional retailer measures sales per square foot.

    The quick-commerce operator needs to think about sales, orders and contribution from each fulfilment location.

    The customer sees a simple app screen.

    Behind that screen is a fairly complex retail operation.

    And this is where I think the conversation around quick commerce needs to become more mature.

    Sales growth alone is not enough.

    Quick Commerce Retailers need to ask harder questions.

    What is the inventory turn?

    What percentage of orders get fulfilled completely?

    How often does the customer find the product unavailable?

    What does picking cost?

    What does delivery cost?

    How much inventory gets damaged?

    How much money is tied up in local inventory?

    And perhaps the most important question:

    Are customers coming back because the platform is genuinely useful, or only because someone is subsidising the order?

    These questions will become increasingly important as the sector matures.

    There is another change that I find particularly interesting.

    The traditional argument used to be:

    Online versus offline.

    I don’t think that is the right argument anymore.

    A physical store can also become a digital fulfilment point.

    A customer can walk into the store and buy something.

    Another customer, sitting two kilometres away, can order from the same inventory.

    The same store can therefore serve both customers.

    This changes the role of the store.

    It can become a place for shopping, product discovery, experience, fulfilment and local inventory — all at the same time.

    So, rather than asking whether quick commerce will replace traditional retail, I would ask a different question:

    How quickly will traditional retailers learn to operate with the same level of convenience? and How efficiently QUick Commerce companies can run like a Retailer to ensure backend excellence and inventory availability at optimium costs

    Because the customer has already changed.

    Once someone gets used to receiving a product within minutes, asking that customer to wait two days for a basic product can feel very different.

    Convenience changes expectations.

    And expectations eventually change retail.

    I don’t think the future of quick commerce will be decided by the fastest delivery time.

    The 10-minute promise helped create the market.

    But speed alone won’t build a sustainable retail business.

    The winners will need to get several things right at the same time:

    Right product. Right location. Right inventory. Right price. Right availability. Right cost.

    That is retail.

    Quick commerce has simply put that retail equation on a much smaller clock.

    And perhaps that is the real story.

    Quick commerce started by promising to deliver faster.

    It is now trying to change the way we shop.

    The next phase will tell us whether it can also change the economics of retail.

  • India’s Skincare Market: Who Is Winning, Who Is Struggling and What Comes Next?

    India’s Skincare Market: Who Is Winning, Who Is Struggling and What Comes Next?

    India’s Skincare Market: Who Is Winning, Who Is Struggling and What Comes Next?

    India’s skincare market is growing. But the bigger story is not growth. It is the redistribution of growth.

    Consumers are moving away from generic skincare and demanding ingredients, efficacy, transparency and convenience. At the same time, digital-first brands are moving offline, legacy FMCG brands are upgrading their portfolios, and global companies are acquiring successful Indian brands.

    So, who actually dominates the market today?

    And more importantly — which brands are building the strongest position for 2026 and beyond?

    This article looks at the current state of India’s skincare industry, the leaders, the challengers, their key problems, what is driving growth and where the market is heading.

    What you should learn from this article

    1. Who currently dominates Indian skincare?
    2. Which brands are gaining momentum?
    3. What is driving consumer demand?
    4. Why are some D2C brands struggling despite high sales?
    5. What will shape the skincare market from 2026 onwards?

    1. First, understand the market

    Estimates put India’s skincare market at roughly $2.7–3.2 billion in 2025, depending on how skincare is defined. Facial care represents approximately 85% of the category.

    The market is growing at roughly 7–10% annually, but growth is becoming increasingly fragmented.

    The structural picture

    HUL remains the clear company-level leader with around 28% retail value share in 2025.

    But there is an important warning:

    HUL’s share has fallen from around 37% in 2020 to 28% in 2025.

    That tells us something important.

    The leader is still leading — but the market is becoming much more competitive.

    Market leadership snapshot

    HUL                    ████████████████████████████ 28%
    Top 5 players combined ██████████████████████████████████████████████████ ~50%
    Others                 █████████████████████████████████████████████████

    Note: Brand-level market shares are not consistently publicly disclosed. The 28% figure refers to HUL’s company-level skincare value share, not Ponds alone.

    The competitive battlefield now includes HUL, Beiersdorf, L’Oréal, P&G, Honasa and fast-growing independent brands such as Plum, alongside strong Ayurvedic and prestige players.


    2. Who is winning?

    The market can broadly be divided into four groups:

    Legacy FMCG: Ponds, Lakmé, Vaseline, Garnier Global premium-mass: Nivea, Olay, L’Oréal Paris Digital-first challengers: Mamaearth, The Derma Co, Minimalist, Plum Ayurvedic/premium heritage: Himalaya, Forest Essentials, Biotique, Kama Ayurveda

    The interesting part?

    The fastest growth is increasingly coming from brands that combine science + digital discovery + omnichannel distribution.

    Article content

    3. Brand-by-brand: Current State

    Ponds — Strong leader, but facing disruption

    Ponds remains one of HUL’s biggest skincare engines and benefits from enormous distribution across general trade, modern trade, e-commerce and quick commerce.

    HUL has been repositioning Ponds away from its traditional tone/fairness associations toward science-led premium skincare.

    Current state: Strong scale and distribution.

    Key challenge: Defend leadership while younger consumers shift toward ingredient-led brands.

    What Ponds needs to do: Convert its enormous reach into stronger relevance among Gen Z and premium skincare consumers.


    Lakmé — Powerful ecosystem, but skincare must keep evolving

    Lakmé benefits from its strong brand recognition, modern trade presence, salons, e-commerce and mass distribution.

    Its expansion into products such as retinol shows the shift toward science-backed skincare.

    Current state: Strong legacy brand with a powerful beauty ecosystem.

    Key challenge: Maintain relevance as consumers increasingly evaluate products by ingredients and efficacy rather than brand heritage alone.


    Nivea — Mature growth, excellent profitability

    Nivea generated approximately ₹1,540 crore revenue in India in FY25, while net profit jumped sharply.

    That is an important signal.

    Revenue was almost flat, but profitability improved dramatically.

    Current state: Mature but financially strong.

    Key challenge: Reignite volume/value growth in a slowing mass market.

    Its Sanand manufacturing facility also shows how localization can reduce import dependence and improve supply-chain resilience.


    Olay — Strong premium positioning

    Olay remains an important premium-mass skincare player, particularly in anti-ageing and brightening.

    Its challenge is not brand awareness. It is winning the modern Indian skincare conversation against highly visible serum and active-based challengers.

    Current state: Strong premium positioning.

    Key challenge: Deliver enough innovation and local relevance to justify its premium.


    Garnier & L’Oréal Paris — Winning through innovation and accessibility

    L’Oréal is benefiting from strong skincare momentum, particularly through Vitamin C, UV protection, glycolic acid and brightening products.

    Garnier has another advantage: it can take ingredient-led skincare into mass markets through affordable formats.

    Current state: One of the strongest combinations of science, marketing and distribution.

    Key challenge: Maintain innovation while protecting affordability.


    Mamaearth — From growth-at-any-cost to profitable growth

    Mamaearth is perhaps the most important D2C case study.

    Honasa’s FY25 revenue reached approximately ₹2,067 crore, but PAT declined 34% to ₹73 crore while advertising remained extremely high.

    Then came FY26.

    Revenue increased approximately 16% to ₹2,392 crore, while PAT jumped 175% to ₹200 crore.

    This is a major lesson:

    The D2C model is not dead. Undisciplined D2C economics are.

    Current state: Recovery and restructuring.

    Key challenge: Sustain growth without excessive advertising and channel costs.


    The Derma Co — One of the strongest challengers

    The Derma Co represents the new Indian skincare consumer better than almost any other brand.

    Its proposition is simple: actives, efficacy and dermatological credibility.

    It crossed approximately ₹750 crore ARR and was recognized as India’s No. 1 sunscreen brand by Euromonitor for CY24.

    Current state: High-growth challenger.

    Key challenge: Scale offline without losing its science-led identity and profitability.


    Minimalist — A strategic success story

    Minimalist has become one of India’s strongest examples of ingredient-led skincare.

    Founded in 2020, it reached more than ₹500 crore ARR and remained profitable before HUL acquired a 90.5% stake for approximately ₹2,706 crore.

    The acquisition says a lot about the future.

    Global-scale FMCG distribution + D2C innovation is becoming a powerful combination.

    Current state: High-quality challenger backed by HUL.

    Key challenge: Scale dramatically without diluting consumer trust and brand authenticity.


    Plum — Quietly building a healthier model

    Plum grew approximately 28% to ₹515 crore in FY26 and had already turned profitable in FY25.

    Its model is increasingly omnichannel, with offline contributing around 30% of revenue.

    Current state: One of the more balanced D2C success stories.

    Key challenge: Scale while maintaining unit economics.


    Himalaya — Heritage remains a competitive advantage

    Himalaya continues to benefit from strong pharmacy and general-trade distribution, Ayurvedic credibility and international presence.

    Unlike many newer brands, its heritage itself is an asset.

    Current state: Strong mass and international presence.

    Key challenge: Make traditional herbal positioning relevant to a younger consumer increasingly asking for clinical evidence and active ingredients.

    Article content

    4. What is actually driving the market?

    Five forces are reshaping skincare:

    1. Ingredient awareness Consumers now actively search for niacinamide, Vitamin C, retinol, salicylic acid and SPF.

    2. Premiumization Consumers are moving from basic creams toward serums, sunscreens, targeted treatments and multi-step routines.

    3. Social discovery Influencers, dermatologists and social media increasingly shape product discovery.

    4. Quick commerce Beauty sales through quick commerce are growing dramatically. Face wash, sunscreen and other repeat-use products fit the model particularly well.

    5. Omnichannel expansion The winning model is no longer pure D2C.

    It is:

    D2C + marketplaces + modern trade + general trade + quick commerce.


    5. The biggest challenges ahead

    The industry has six major pressure points:

    CAC inflation: Advertising-led growth is becoming expensive.

    Margin pressure: Quick-commerce commissions and visibility costs can erode profitability.

    Channel conflict: Different prices across websites, marketplaces and stores can damage brand economics.

    Generic natural positioning: “Natural” alone is no longer enough.

    Import dependency: Specialty actives, UV filters and other ingredients remain vulnerable to global supply chains.

    Trust: Counterfeits, grey-market inventory and poor storage can damage consumer confidence.

    The next phase will therefore reward operational discipline as much as marketing creativity.


    6. What changes from 2026 onwards?

    I see six major trends.

    1. Science will beat vague claims

    “Natural” will not disappear.

    But natural + evidence will outperform natural alone.

    2. Sunscreen becomes a major battlefield

    Daily SPF adoption is still expanding, creating a large opportunity for brands that can combine efficacy, texture, affordability and education.

    3. Quick commerce becomes a strategic channel

    Brands will stop treating Blinkit, Zepto and Instamart only as distribution channels.

    They will increasingly treat them as media + retail + convenience platforms.

    4. D2C brands will consolidate

    The market will favour brands with strong repeat purchase, healthy contribution margins and differentiated products.

    Revenue alone will no longer impress investors.

    Profitable growth will.

    5. M&A will accelerate

    The HUL–Minimalist transaction and global interest in premium Indian beauty demonstrate the strategic value of Indian skincare brands.

    Expect more consolidation.

    6. India can become a skincare manufacturing and export hub

    Ayurvedic heritage, local manufacturing and cost-efficient formulation can create an export opportunity — particularly in GCC, Africa and other emerging markets.


    The final takeaway

    India’s skincare market is not simply growing. It is changing shape.

    HUL still dominates structurally.

    Nivea remains financially strong.

    L’Oréal is winning through innovation.

    The Derma Co is building serious momentum.

    Minimalist has already attracted strategic acquisition.

    Mamaearth is demonstrating that disciplined D2C economics can work.

    Plum is proving profitability can coexist with growth.

    Himalaya continues to leverage heritage and distribution.

    The real winner of 2026 and beyond, however, will not necessarily be the brand with the biggest advertising budget.

    It will be the brand that can combine:

    Efficacy + Trust + Innovation + Distribution + Repeat Purchase + Profitable Growth.

    That is where India’s next skincare battle will be fought.

    This study is an assessment of a writer. Please do your own research and decide way forward. Don’t depend alone what we are writing and expressing our views.

  • What 5,200 Customer Reviews Reveal About Process Failures in Quick Commerce

    What 5,200 Customer Reviews Reveal About Process Failures in Quick Commerce

    What Customer Complaints Can Tell Us About Quick Commerce Operations
    A customer complaint rarely starts where the customer experiences it.
    A late delivery may not be a delivery problem.
    A delayed refund may not be a customer-support problem.
    A cancelled order may not be a cancellation problem.
    And that is exactly where many organisations get improvement wrong.
    They respond to the visible complaint instead of investigating the process that created it.
    Quick commerce makes this challenge even more interesting.
    The customer sees a simple promise: fast, convenient and reliable delivery.
    Behind that promise, however, sits a complex chain of inventory, store operations, picking, packing, technology, rider allocation, delivery, payments, refunds and customer support.
    When that chain breaks, the customer does not see the process.
    They see the outcome. And they complain about it.
    That makes customer complaints far more than customer-service data.
    They can be early signals of process variation, waste and defects.
    With that perspective, we analysed customer reviews across five major quick-commerce platforms to understand what recurring complaints could tell us about the underlying customer journey.
    The Objective
    The purpose was not to rank companies or identify winners and losers.
    Instead, we wanted to answer three questions:

    What are customers complaining about most frequently?
    What patterns emerge when all complaints are analysed together?
    Which recurring problems may require a structured Lean Six Sigma investigation?

    The study analysed 5,200 recent customer reviews across the five platforms.
    Of these, 1,401 reviews—or 26.9%—contained identifiable complaints.
    The remaining reviews were positive or did not contain a clearly identifiable complaint.
    In other words, roughly one in every four reviews contained a signal that something in the customer journey had not worked as expected.

    What Did the Combined Data Reveal?
    When all five platforms were analysed together, complaints were not concentrated around one single operational problem.
    The major themes included:

    Refund and customer-support issues
    General dissatisfaction
    Unclassified complaints
    Delivery delays
    Product quality issues
    Missing or incorrect items
    Pricing and charge-related concerns
    Order cancellations
    Trust-related concerns
    Technical and app-related problems

    One finding stood out immediately.
    A significant number of complaints were broad, emotional or difficult to classify into one specific defect.
    When a customer says, “Worst experience”, the dissatisfaction is clear. The root cause is not.
    Was the problem delivery?
    Was it the product?
    Was it the refund?
    Was it customer support?
    Or did several process failures combine to create one poor experience?
    This is where complaint analysis alone reaches its limit.
    It can tell us where customers feel the pain.
    It cannot always tell us why the process created it.

    The Pattern Was Not the Same for Every Company
    The most interesting insight was not simply the overall number of complaints.
    It was how differently the complaint patterns appeared across the platforms.
    One platform showed a significantly higher complaint rate, with concerns concentrated around:

    Refunds
    Customer support
    Product quality

    Another showed a stronger delivery-related pattern.
    Another had relatively greater concerns around pricing and charges.
    Another showed a combination of delivery delays and order cancellations.
    This distinction matters.
    These companies operate in the same industry and compete for similar customers.
    But the customer-facing defects are not identical.
    That means a generic “customer experience improvement programme” may be too broad to solve the real problem.
    Each complaint pattern points towards a different part of the process that needs investigation.

    Company Comparison

    Article content


    What Does This Mean from a Lean Six Sigma Perspective?
    The data does not tell us what solution each company should implement.
    And it should not.
    Jumping directly from a complaint to a solution is one of the most common mistakes in improvement work.
    A late delivery does not automatically mean more riders are required.
    A refund delay does not automatically mean more customer-service employees are needed.
    A cancellation does not automatically mean inventory is the problem.
    The visible complaint is the symptom.
    The real question is:
    Where did the process begin to fail?
    Based on the patterns identified in this study, organisations may need structured Lean Six Sigma projects around five broad areas.
    1. Refund and Customer Support
    Key questions include:

    Where does waiting occur?
    Why do some cases take longer to resolve?
    Why are repeat customer interactions required?
    Where do handoffs and escalations create variation?

    2. Delivery Reliability
    The customer sees a late delivery.
    The investigation needs to trace the entire journey:
    Order → Picking → Packing → Rider Allocation → Dispatch → Delivery
    The critical question is:
    At which point did the variation enter the process?
    3. Product and Order Quality
    For missing, incorrect, damaged or poor-quality items:

    Where did the defect originate?
    Inventory?
    Picking?
    Packing?
    Storage?
    Delivery?

    4. Order Cancellations
    A cancellation is often the final visible outcome of an earlier failure.
    The investigation needs to understand what happened before the order reached that point.
    5. Pricing, Transparency and Trust
    Some complaints may reflect an operational defect.
    Others may reflect a gap between:
    What the customer expected and What the process delivered or communicated.
    Both require investigation.

    The Bigger Lesson
    The strongest takeaway from this study is simple:
    Customer complaints are process signals.
    A customer sees the final failure.
    The organisation needs to trace that failure backwards.
    A delivery complaint may have started long before dispatch.
    A refund complaint may have nothing to do with the person speaking to the customer.
    A missing product may have entered the process before the order was packed.
    That is why these findings should not immediately lead to solutions.
    They should lead to better questions.

    Why are refunds delayed?
    Why do customers need repeated support interactions?
    Why does delivery performance vary?
    Why do orders get cancelled?
    Why do incorrect or damaged products reach customers?
    Why do customers perceive some charges or transactions as unclear?

    These are not simply customer-service questions.
    They are process questions.
    And process questions require structured root-cause investigation.

    The Way Forward
    This study is a starting point, not a diagnosis.
    It identifies where customers experience recurring problems.
    The next step is to investigate why those problems occur.
    That is where Lean Six Sigma can provide a structured path:
    Customer Complaint → Problem Definition → Measurement → Root-Cause Analysis → Improvement
    The biggest mistake would be to assume that the visible complaint is also the root cause.
    It rarely is.
    Quick commerce will continue to compete on speed.
    But the next competitive advantage may not come from delivering a few minutes faster.
    It may come from something much harder to build:
    A process that works consistently—even when things do not go as planned.
    Comments

    Comments settings


    Photo of Gaurang Govind

    Like

    Comment

    Sharerce

  • The Real Challenge in Fashion Retail: Turning Inventory into Profitable Sales

    The Real Challenge in Fashion Retail: Turning Inventory into Profitable Sales

    In fashion retail, the biggest problem is rarely buying merchandise.

    The real problem is what happens after the merchandise arrives.

    A retailer can have experienced buyers, strong vendor relationships, detailed market research, carefully planned ranges and significant seasonal budgets. Yet, at the end of the season, the same retailer may still find itself sitting on unsold inventory and offering deep discounts to clear it.

    That is the fundamental challenge of fashion retail.

    The question is not simply:

    “Did we buy the right merchandise?”

    The more important question is:

    “How efficiently did we convert the merchandise we bought into profitable sales?”

    Because in fashion retail, inventory does not just represent stock. It represents committed capital, planned gross margin, future markdown risk and, ultimately, the quality of merchandising decisions.

    Fashion Buying Is a High-Stakes Commitment

    A fashion buyer or merchandiser does not wake up every morning and purchase inventory based on yesterday’s sales.

    Fashion buying works very differently.

    Merchandising teams make commitments well in advance of the season. They study trends, review vendor presentations, analyse previous performance, understand customer preferences and build product ranges across categories.

    Typically, the merchandise portfolio contains three broad layers.

    The first is core merchandise. These are products that customers expect to find throughout the year. They may not always create excitement, but they provide consistency and predictable demand.

    The second is seasonal or festival merchandise. These products are designed around specific periods—festivals, weather changes, weddings or other demand peaks.

    The third and most challenging category is fashion merchandise.

    Fashion moves quickly. Consumer preferences shift. Colours, silhouettes, fabrics and styles can suddenly become desirable—or lose relevance.

    Retailers cannot ignore fashion because customers expect freshness. However, fashion buying involves significantly higher risk.

    And then comes another complex variable: size.

    The same product may perform differently across geographies because customer body profiles and size preferences differ. A size mix that works extremely well in Punjab may not work in the Northeast. A retailer operating across multiple regions cannot simply apply one universal size curve everywhere.

    Therefore, before the season even begins, the merchandising team has already made a series of critical decisions:

    What categories should we buy?

    Which designs should we select?

    How many options should we carry?

    How much inventory should we commit?

    What should be the size ratio?

    When should deliveries arrive?

    And how much of the budget should we allocate to each product category?

    Everything may appear perfectly planned.

    But fashion retail rarely follows the plan exactly.

    The Problem Is Not Always Demand Forecasting

    When inventory does not sell, the first solution many people suggest is demand forecasting.

    Better forecasting is certainly useful—but it does not solve the entire problem.

    Fashion retailers often place orders months before the merchandise reaches the store. Production has lead times. Vendors require advance commitments. Seasonal products may only be available during a specific manufacturing window.

    A retailer cannot simply wait until the season begins, observe customer demand and then immediately replenish the winning products.

    By the time the demand becomes clear, the buying decision may already have been made.

    Vendor capability also plays a major role.

    If a vendor can manufacture and replenish products frequently, the retailer can operate with greater flexibility. The retailer can test the market, identify winning styles and reorder them.

    But many seasonal and fashion products do not offer that luxury.

    They are produced for a particular season, ordered in advance and supplied according to a pre-decided delivery schedule.

    That means fashion retail is not merely a forecasting problem.

    It is a commitment and inventory-risk management problem.

    The quality of the buying decision depends not only on predicting what customers will buy, but also on understanding:

    How much should we commit before demand becomes visible?

    How much flexibility does our supply chain provide?

    How quickly can we react if the product performs differently than expected?

    These questions often matter more than improving the forecasting model by a few percentage points.

    The ₹100 Inventory Question

    Let us simplify the entire challenge.

    Imagine a retailer purchases merchandise worth ₹100.

    The most important question is not simply whether that ₹100 eventually sells.

    The important question is:

    At what price did it sell?

    That ₹100 worth of inventory can move through multiple stages.

    The first portion sells at full price.

    This is the most profitable outcome. The retailer captures the planned margin and validates the quality of the buying and merchandising decisions.

    The second portion sells during a planned festival or promotional period.

    The retailer may offer discounts, but these discounts are already part of the commercial plan. The retailer expects lower percentage margins but anticipates significantly higher sales volumes.

    This is not necessarily a problem.

    In fact, a well-planned festival period can generate substantial gross margin in absolute value because of the higher sales volume.

    The real problem begins with the third layer.

    This is the inventory that remains after the main selling opportunity has passed.

    Perhaps the design did not work.

    Perhaps the colour was wrong.

    Perhaps the fashion trend moved in another direction.

    Perhaps customers bought only certain sizes.

    The retailer may have sold Medium and Large but still be left with significant quantities of Small and Extra Large.

    Or the retailer may have sold one option within a product line while other options remained untouched.

    At this stage, inventory stops behaving like an asset.

    It begins behaving like a liability.

    Unsold Inventory Destroys Gross Margin

    Once merchandise misses its planned selling window, the retailer faces difficult choices.

    The first option is to offer deeper discounts.

    The second is to carry the inventory into the next period.

    The third is to attempt alternative channels to liquidate the stock.

    Each option carries a cost.

    Deep discounting directly affects gross margin.

    Carrying inventory forward blocks working capital and creates additional risk.

    And alternative liquidation channels require careful execution to avoid damaging the brand or cannibalising regular store sales.

    This is why gross-margin performance should never be evaluated only through sales growth.

    A retailer can achieve strong sales and still destroy profitability if too much inventory eventually moves through deep markdowns.

    The merchandising team’s real efficiency lies in its ability to convert committed inventory into sales at the right margin levels.

    A buyer who purchases ₹10 crore worth of merchandise is not necessarily successful because ₹10 crore eventually sells.

    The buyer becomes successful when a high proportion of that merchandise sells at full price or within planned promotional margins—and only a limited portion falls into distress liquidation.

    That is the difference between buying merchandise and managing inventory productivity.

    Every Fashion Retailer Needs a Margin Waterfall

    Retailers should stop looking at inventory as one large number.

    Instead, they should create a weekly inventory and margin waterfall.

    Every week, the merchandising and leadership teams should be able to answer four simple questions.

    How much inventory have we sold at full price?

    How much have we sold at planned festival or promotional prices?

    How much have we sold through additional markdowns?

    How much inventory is still left and at risk?

    This simple framework can dramatically improve decision-making.

    Because the problem becomes visible before the end of the season.

    If the retailer waits until the annual review to discover that gross margin has missed the budget, it is already too late.

    By then, the unsold inventory has accumulated, markdowns have accelerated and the organisation has lost its ability to take corrective action.

    Weekly visibility changes the conversation.

    The buyer no longer says, “Sales are looking good.”

    The organisation asks:

    Are we selling the right inventory at the right margin?

    That is a far more powerful question.

    Predict Gross Margin Before the Quarter Ends

    Once retailers track inventory through these different selling layers, they can begin predicting gross-margin performance much earlier.

    For example, if the retailer notices that a growing proportion of inventory is moving into deeper markdowns, management can immediately estimate the impact on future gross margin.

    Similarly, if full-price sell-through remains strong, the retailer can protect margin expectations even before the season ends.

    This creates a much more dynamic approach to gross-margin management.

    Instead of reviewing profitability after the quarter closes, the retailer can manage profitability while the season is still active.

    The merchandising team can identify slow-moving categories.

    Stores can rebalance inventory.

    Winning products can receive greater visibility.

    Slow-moving sizes can move to geographies where demand is stronger.

    Promotional activity can become targeted rather than broad.

    And management can intervene before the stock reaches the stage of distress liquidation.

    Alternative Channels Can Protect Inventory Value

    Today, fashion retailers also have an advantage that did not exist at the same scale a few years ago.

    They have direct access to customers through digital channels.

    Video commerce and live product selling have become particularly effective tools for inventory liquidation.

    For example, a retailer operating in the Northeast may find itself with merchandise that is not performing strongly in its local stores. Instead of immediately applying deep in-store discounts, the retailer can showcase the merchandise through video-led selling and reach customers beyond the physical catchment area.

    The objective is not simply to clear stock.

    The objective is to clear stock intelligently.

    A retailer should always try to find the highest-value channel available for unsold merchandise before moving to aggressive markdowns.

    Digital selling, live commerce, targeted customer databases and inter-store inventory transfers can all provide additional opportunities to recover value.

    The key is to act early.

    The longer a retailer waits, the fewer options remain.

    The KPI That Fashion Retailers Should Watch Every Week

    Fashion retail leaders need to move beyond traditional sales reporting.

    The most important weekly KPI framework should connect inventory, sell-through and realised margin.

    A merchandising team should know how much of its inventory has moved through:

    • Full-price sales
    • Planned festival or promotional sales
    • Additional markdown sales
    • Unsold and ageing inventory

    This should not remain a year-end analysis.

    It should become a weekly management discipline.

    Because the moment a retailer understands the composition of its sales, it also begins to understand the future composition of its gross margin.

    And that is where better decisions begin.

    The Bottom Line

    Fashion retail will always involve uncertainty.

    Trends will change.

    Customers will surprise buyers.

    Sizes will behave differently across regions.

    Some designs will outperform expectations while others will fail completely.

    No forecasting system can eliminate these realities.

    But retailers can control how quickly they identify risk and how intelligently they respond to it.

    The strongest fashion retailers will not necessarily be the ones that predict every trend perfectly.

    They will be the ones that build a more efficient system for converting inventory into profitable sales.

    Because ultimately, the real measure of merchandising success is not how much merchandise a buyer purchased.

    It is not even how much merchandise the retailer sold.

    The real measure is much more powerful:

    How much of the inventory sold at full price, how much sold within planned promotional margins, how much required additional discounting—and how much was left behind?

    When a retailer starts reviewing these numbers every week, inventory stops being a year-end problem.

    It becomes a business variable that management can actively control.

    And in fashion retail, where every buying decision carries risk, that visibility can be the difference between meeting the gross-margin budget and watching it disappear into markdowns.

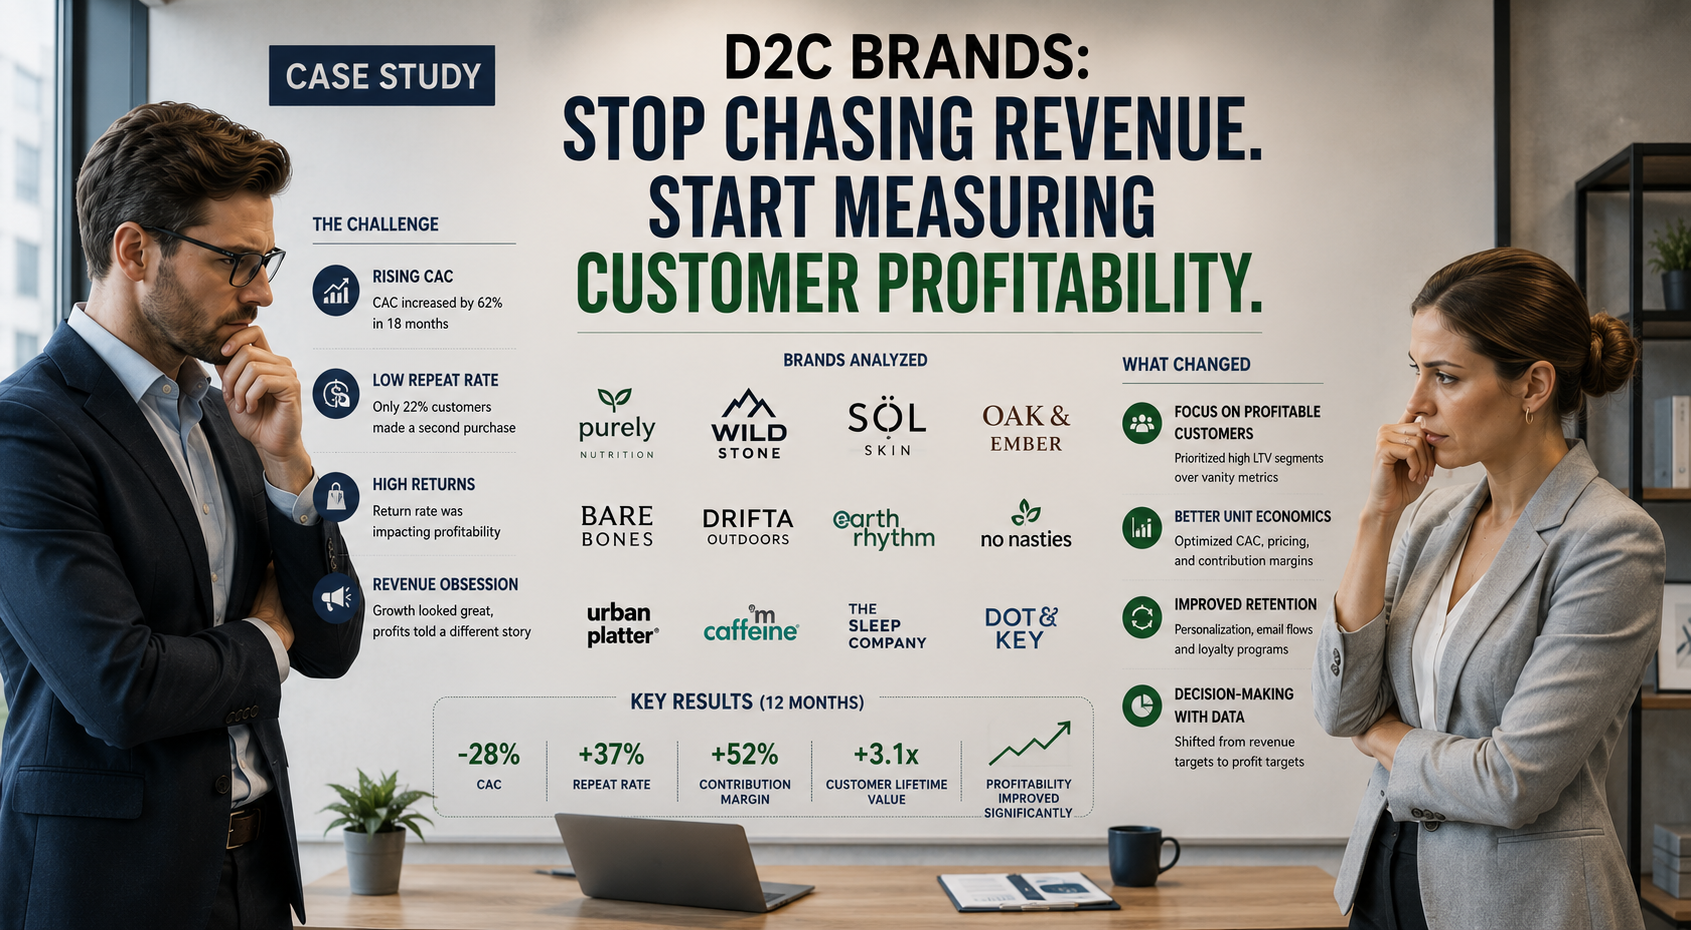
  • D2C Brands: Stop Chasing Revenue. Start Measuring Customer Profitability.

    D2C Brands: Stop Chasing Revenue. Start Measuring Customer Profitability.

    For years, D2C has been presented as the smarter way to build a consumer brand.

    Go directly to the customer. Avoid expensive stores. Build your own digital identity. Use social media to acquire customers. Scale quickly.

    It sounds simple.

    But the reality is very different today.

    D2C Brands: Stop Chasing Revenue. Start Measuring Customer Profitability.

    Customer acquisition costs are rising. Competition is increasing. Online marketplaces are crowded. Consumers have endless choices. And customer loyalty is becoming harder to earn.

    So the real question for a D2C brand today is not:

    “How do I sell more online?”

    It is:

    “How does my customer actually make a purchase decision, and where should I be available when that decision happens?”

    That requires looking beyond the D2C label.


    The D2C customer is not one customer

    One of the biggest mistakes brands make is treating their online customer as a single segment.

    India has very different consumer groups—from affluent consumers to upper-middle-class, middle-income and value-conscious households.

    But income alone does not determine behaviour.

    Category determines behaviour.

    A consumer may be extremely price-sensitive when buying groceries but may pay a premium for skincare.

    The same person may compare five furniture brands before buying a sofa but purchase a familiar FMCG product almost automatically.

    That is why customer behaviour has to be understood category by category, occasion by occasion and need by need.

    Consider a few examples.

    Fruits & vegetables

    Freshness, availability, convenience and price can dominate the decision.

    Furniture

    Durability, finish, design, comfort, quality, price and confidence in the product become important.

    Beauty & cosmetics

    Product efficacy, ingredients, packaging, reviews, colour, price, trust and brand image can all influence the decision.

    There is therefore no universal D2C customer.

    There are category-specific customers with different reasons to buy.


    The customer knows more—but not necessarily enough

    The digital consumer today has extraordinary access to information.

    With a few clicks, customers can compare:

    • Prices
    • Reviews
    • Features
    • Competitors
    • Offers
    • Influencer opinions
    • Product demonstrations
    • Customer experiences

    But information availability does not automatically create understanding.

    The customer may see ten products but still struggle to decide which one is right.

    That is where trust, reviews, brand credibility, product experience and availability become critical.

    And this is where physical retail still has an important role.

    A customer can touch a product.

    See its finish.

    Try it.

    Speak to someone.

    Understand the difference between two products.

    And sometimes, simply seeing the brand in a physical environment creates confidence.


    The biggest D2C problem today: Customer acquisition

    Digital platforms have made customer access easier.

    They have also made competition much more intense.

    A D2C brand is competing for attention on the same platforms as hundreds or thousands of other brands.

    Meta, Instagram, YouTube, Google and marketplaces can generate enormous reach.

    But reach comes at a price.

    As more brands compete for the same audience:

    Customer acquisition becomes more expensive.

    And if the customer makes one purchase and never returns, the economics become even more difficult.

    This creates a dangerous cycle:

    Higher advertising spend → higher acquisition cost → lower contribution → greater dependence on repeat purchases.

    Therefore, the real question is not how much you spend to acquire a customer.

    It is:

    How much value can you generate from that customer over time?


    D2C and retail: Are the costs really that different?

    This is where I believe many D2C entrepreneurs should take a closer look at their numbers.

    Retail has obvious costs:

    Rent + people + inventory + utilities + operations.

    D2C has a different-looking cost structure:

    Technology + digital marketing + customer acquisition + fulfilment + returns/refunds + inventory + customer service.

    The cost heads are different.

    But the underlying economics are surprisingly similar.

    Both businesses have to:

    • Hold inventory
    • Acquire customers
    • Fulfil orders
    • Manage returns
    • Build trust
    • Provide customer service
    • Maintain technology/processes
    • Generate repeat purchases

    So the assumption that “D2C is automatically cheaper than retail” needs to be challenged.

    It depends entirely on the category, ticket size, margins, repeat rate, geography, assortment and customer acquisition economics.


    So should D2C brands enter retail?

    In many cases, yes—but not blindly.

    Retail can provide something that digital advertising cannot always provide:

    Physical discovery and local trust.

    Suppose a brand establishes a profitable store in a particular catchment.

    It understands the local customer.

    It gets the assortment right.

    Its pricing works.

    Its people are trained.

    Its product mix generates healthy margins.

    And it builds repeat customers within a 3–4 km radius.

    Now the brand has something extremely valuable:

    A proven local business model.

    The next opportunity is to replicate that model in another geography.

    Then another.

    Then another.

    That is very different from simply opening stores because the brand wants a physical presence.


    The future may not be D2C versus retail

    I believe the more relevant question is:

    Why choose one when the customer is using both?

    A consumer may discover your brand on Instagram.

    Read reviews on Google.

    Compare prices on a marketplace.

    See the product in a store.

    Order it through quick commerce.

    Buy again from your website.

    And recommend it to a friend on social media.

    The customer does not think in channels.

    The customer thinks:

    “I want the right product, at the right price, with minimum effort and maximum confidence.”

    Brands need to think the same way.


    But there is a warning for D2C brands

    Do not rush into retail simply because everyone else is doing it.

    Before opening a store, ask:

    Do I have enough SKUs?

    Is my assortment strong enough?

    Can I create a meaningful store proposition?

    Are my margins sufficient?

    Can the store generate repeat business?

    Do I understand the catchment?

    Can I train people to sell the product properly?

    A store cannot become a physical warehouse for your online products.

    It needs a reason to exist.

    The assortment, store experience, pricing, visual merchandising and customer interaction must come together as one proposition.


    The next competitive advantage: Operational excellence

    For D2C brands, the next phase will not be won simply by having a better Instagram campaign.

    It will be won through better execution.

    Brands need systems that tell them:

    Where is the customer dropping off?

    Why is the customer not completing the purchase?

    Why are returns increasing?

    Which SKU is generating repeat purchases?

    Which geography is profitable?

    Which channel is acquiring the best customers?

    Which customers are worth retaining?

    Where is inventory getting stuck?

    And most importantly:

    What does it cost to serve each customer?

    Technology will play a major role here.

    But technology alone is not the answer.

    Data + process + people + execution have to work together.


    My advice to D2C brands

    Before spending the next ₹1 crore on customer acquisition, stop and calculate the economics.

    Compare:

    D2C economics vs Retail economics vs Marketplace economics vs Quick Commerce economics.

    Look at the complete picture—not just revenue.

    Measure:

    CAC Customer Lifetime Value Contribution Margin Repeat Purchase Rate Return Rate Inventory Turns Gross Margin Cost-to-Serve Store Productivity GMROF

    Then decide where your customer should find you.

    Because the future is unlikely to belong to brands that are only D2C.

    It will belong to brands that can move seamlessly across D2C + retail + marketplaces + quick commerce, while maintaining healthy unit economics.


    The final thought

    The D2C opportunity in India is still enormous.

    But the easy growth phase is getting harder.

    Consumers have more choices.

    Advertising is more expensive.

    Competition is intense.

    Loyalty has to be earned repeatedly.

    And profitability can disappear very quickly behind attractive revenue numbers.

    So don’t ask:

    “How fast can I acquire customers?”

    Ask:

    “How profitably can I acquire, serve and retain them?”

    And don’t ask:

    “Should I be D2C or retail?”

    Ask:

    “Where does my customer want to buy from me—and which combination of channels creates the strongest business?”

    D2C may have started the journey by removing the middleman.

    The next stage is about removing the friction between the customer, the brand and a profitable transaction.

    That is where the real scale will come from.

    #D2C #Retail #Ecommerce #ConsumerBehaviour #CustomerAcquisition #QuickCommerce #RetailStrategy #BusinessTransformation #OperationalExcellence #CustomerExperience #Profitability #IndianRetail

  • India Retail 2024–2027: From Store Expansion to Intelligent Retail Expansion I A retail case study on what changed, what is coming next, and what ret

    India Retail 2024–2027: From Store Expansion to Intelligent Retail Expansion I A retail case study on what changed, what is coming next, and what ret

    The Hook

    India’s retail expansion story is entering its next phase.

    The question is no longer:

    “How many stores can we open?”

    The question is:

    “How intelligently can we expand while protecting productivity, profitability and customer relevance?”

    Post banner

    Between 2024 and 2026, India’s leading retailers significantly increased their physical footprints while quick commerce simultaneously created a completely different retail proposition: availability at the doorstep within minutes.

    Now the real battle is moving towards Tier 2, Tier 3 and emerging consumption centres.

    And I believe the next two years will be less about the race for store count and more about the race for better retail economics.

    What happened between 2024 and 2026?

    Three examples illustrate the direction.

    Reliance Retail

    Reliance Retail increased its store network from 19,340 stores in FY2025 to 20,160 stores in FY2026, while gross revenue increased from ₹3.31 lakh crore to approximately ₹3.71 lakh crore. Its Smart Bazaar network crossed 1,000 stores, with a significant part of that network serving Tier 2 and smaller markets.

    More importantly, Reliance is combining physical stores, digital commerce and hyperlocal commerce rather than treating them as separate businesses.

    Trent’s Zudio

    Zudio reached 963 stores across 313 cities by FY2026, compared with 765 stores in FY2025 and 545 stores in FY2024. The company’s own reporting highlights accessibility, sharp price points, in-house merchandise and rapid expansion as key elements of the model.

    Avenue Supermarts

    Avenue Supermarts, the operator of the DMart chain, moved from 365 stores in FY2024 to 415 in FY2025 and 500 in FY2026.

    The FY2026 expansion is particularly interesting: 85 stores were added, including 45 stores in Tier 2+ markets, while the company entered 39 new cities, 34 of them Tier 2+. It also entered Uttar Pradesh, Haryana, Odisha, Uttarakhand and Goa.

    The message from these examples is clear:

    India’s organised retail opportunity is moving deeper into the country. This we all know.

    But there is another force changing the game.

    The Quick-Commerce Challenge

    Quick commerce has changed the consumer’s definition of convenience.

    The customer no longer thinks:

    “I need to visit a store.”

    The customer increasingly thinks:

    “I need it now.”

    Blinkit, Swiggy Instamart and Zepto have built large dark-store networks, while Amazon and Flipkart are now increasing their investments in rapid delivery.

    In June 2026, Reuters reported that Amazon planned to expand its rapid-delivery service to 300 Indian cities, while Flipkart was targeting approximately 1,500 quick-commerce locations.

    This creates an interesting future scenario.

    Traditional retailers will increasingly have stores.

    Quick-commerce companies will increasingly have dark stores.

    E-commerce companies will increasingly combine warehouses, marketplaces and rapid fulfilment.

    The consumer will simply choose whichever channel delivers the best combination of:

    Price + availability + speed + trust + assortment + experience.

    My Forecast for 2026–2027

    1. Tier 2 and Tier 3 will become the primary expansion laboratory

    I expect retailers to become more aggressive in smaller cities—but also more selective.

    The next phase will not be:

    “Let’s enter every Tier 2 city.”

    It will be:

    “Let’s identify the right micro-markets inside the right Tier 2 cities.”

    Population alone will not be sufficient.

    Retailers will increasingly evaluate:

    – Catchment population

    – Household income

    – Consumer spending

    – Competition

    – Footfall potential

    – Real-estate cost

    – Logistics cost

    – Delivery density

    – Digital adoption

    – Category potential

    – Store productivity potential

    This means location analytics will become a board-level expansion capability.

    —

    2. Cluster expansion will become more important than isolated expansion

    The next winning model may not be one store in 20 cities.

    It may be five to ten stores in one carefully selected cluster.

    Why?

    Because clustering can improve:

    Supply-chain efficiency → inventory availability → marketing efficiency → management supervision → brand awareness → customer familiarity.

    Retailers should therefore stop measuring expansion only by the number of stores opened.

    They should measure:

    Revenue per cluster.

    Profit per cluster.

    Inventory turns per cluster.

    Supply-chain cost per cluster.

    Customer acquisition cost per cluster.

    This is where retail analytics can transform expansion decisions.

    —

    3. Quick commerce will not kill physical retail—but it will change its role

    This is perhaps the most important prediction.

    Physical stores will increasingly need to answer:

    “Why should the customer visit me?”

    For grocery, the answer could be:

    Better value + larger assortment + monthly shopping + fresh produce + discovery.

    For fashion:

    Trial + experience + instant gratification + newness.

    For electronics:

    Demonstration + advice + service + installation.

    For lifestyle:

    Discovery + experience + social shopping.

    The physical store therefore needs to become more than a transaction point.

    It needs to become a customer-experience and fulfilment asset.

    —

    4. Dark stores will face an operational-quality test

    There is another issue that I believe deserves far greater attention.

    A dark store is still a retail operation.

    Technology can manage orders.

    Technology can generate inventory alerts.

    Technology can optimise delivery routes.

    But people still have to manage:

    Expiry → FEFO → hygiene → temperature → receiving → storage → pest control → picking → product handling.

    Recent food-safety enforcement in Maharashtra illustrates the risk. Authorities inspected quick-commerce establishments and suspended permits at 12 warehouses after identifying issues including cockroach infestations, rodent droppings and other sanitation problems.

    This should not be viewed only as a quick-commerce problem.

    It is an industry-wide retail operations lesson.

    As the network expands, retailers need stronger:

    Retail audits + SOP compliance + training + accountability + store-level ownership.

    —

    5. E-commerce and direct-to-consumer brands will push deeper into smaller cities

    This is another major structural change.

    Smaller-city consumers are not waiting for physical stores.

    They are discovering brands online.

    According to Unicommerce data reported by the India Brand Equity Foundation, Tier 2 and Tier 3 cities were expected to contribute around 66% of new direct-to-consumer orders in FY2026.

    This changes the expansion equation.

    A brand can now enter a city digitally before opening a physical store.

    That creates an important consulting opportunity:

    Digital-first → Data validation → Pilot store → Cluster expansion

    Instead of:

    Store first → Hope for demand → Correct later

    This can significantly reduce expansion risk.

    —

    What should retailers do now?

    Action 1: Build a micro-market expansion model

    Don’t approve a new store only because the city looks attractive.

    Create a scoring model covering:

    Demand + competition + rent + catchment + logistics + digital demand + store economics.

    —

    Action 2: Establish a 12–24 month store maturity dashboard

    Every new store should be tracked against:

    Sales per sq. ft./ GMROF

    Gross margin.

    GMROI.

    Inventory turns.

    Inventory cycle

    Conversion.

    Average basket value.

    Shrinkage.

    Manpower productivity.

    Contribution margin.

    This allows management to distinguish between a temporary maturity issue and a fundamentally weak location.

    —

    Action 3: Design the store and dark store together

    The future will increasingly require omnichannel operating models.

    A physical store may serve:

    Walk-in customers + online orders + click-and-collect + local fulfilment.

    Retailers should therefore redesign:

    Inventory → picking → replenishment → manpower → technology → customer journey

    as one integrated process.

    —

    Action 4: Create independent operational audits- audits are crucial specially third party remove bias

    Expansion multiplies risk.

    Every additional location creates another opportunity for:

    Expiry leakage + shrinkage + poor hygiene + inventory inaccuracies + SOP deviation + manpower inefficiency.

    Retailers should therefore create a structured audit framework covering:

    People + Process + Product + Place + Technology + Compliance.

    —

    Action 5: Treat Tier 2 and Tier 3 as different markets—not smaller metros

    This is critical.

    Consumers in smaller cities may have different:

    Price sensitivities, pack-size preferences, fashion choices, shopping missions, credit behaviour and local brand preferences.

    Retailers should analyse local behaviour before standardising the assortment.

    —

    The Biggest Prediction for 2027

    I believe the retail industry will gradually move from:

    “Expansion at scale”

    to

    “Intelligent expansion at scale.”

    The winners will not necessarily have the largest number of stores.

    They will have the best store economics, supply chain, data systems, customer understanding and execution discipline.

    The next competitive advantage will come from connecting:

    Physical retail + e-commerce + direct-to-consumer + quick commerce + data + supply chain.

    And this will create a new retail equation:

    Right Market × Right Format × Right Assortment × Right Inventory × Right Execution = Profitable Growth

    —

    Final Recap

    The last two years proved that physical retail is not disappearing.

    It is changing.

    Reliance Retail has crossed 20,000 stores.

    Zudio has reached nearly 1,000 stores.

    Avenue Supermarts has reached 500 stores and is pushing deeper into Tier 2+ markets.

    At the same time, quick commerce and e-commerce are moving rapidly into smaller markets.

    So the next two years will not be about choosing between stores and digital.

    They will be about building the right combination.

    For retailers, my recommendation is straightforward:

    Analyse before expanding.

    Pilot before multiplying.

    Cluster before spreading.

    Measure productivity before celebrating footprint.

    Audit operations before scaling.

    And most importantly:

    Build the organisation’s capability at the same speed as you build its footprint.

    Because in the next phase of Indian retail, opening the store may be easy. Running 500 or 5,000 stores consistently will be the real competitive advantage.

    Sources and further reading

    – “Reliance Industries — FY2025–26 Retail Business Overview” (https://reference-url-citation.invalid/7)

    – “Reliance Industries — FY2025–26 Integrated Annual Report” (https://reference-url-citation.invalid/8)

    – “Trent Limited — FY2025–26 Integrated Annual Report” (https://reference-url-citation.invalid/9)

    – “Trent Limited — Annual Reports and Company Filings” (https://reference-url-citation.invalid/10)

    – “Avenue Supermarts — FY2024–25 Annual Report” (https://reference-url-citation.invalid/11)

    – “Motilal Oswal — Avenue Supermarts FY2026 expansion analysis” (https://reference-url-citation.invalid/12)

    – “Reuters — Amazon and Flipkart quick-commerce expansion” (https://reference-url-citation.invalid/13)

    – “Reuters — Food-safety enforcement at quick-commerce warehouses” (https://reference-url-citation.invalid/14)

    – “India Brand Equity Foundation — Tier 2/3 direct-to-consumer growth” (https://reference-url-citation.invalid/15)

    #RetailIndia #RetailStrategy #RetailExpansion #RetailOperations #QuickCommerce #DarkStores #Ecommerce #DirectToConsumer #Tier2Cities #Tier3Cities #OmnichannelRetail #RetailAnalytics #SupplyChain #StoreProductivity #FMCG #RetailConsulting #CustomerExperience #InventoryManagement #GMROI

    Gaurang Govind

    Business Consulting firm

  • RETAIL, D2C, QUICK COMMERCE & E-COMMERCE July 2026 Industry Update Compiled July 13, 2026 

    RETAIL, D2C, QUICK COMMERCE & E-COMMERCE July 2026 Industry Update Compiled July 13, 2026 

    India’s quick-commerce, D2C and e-commerce ecosystem entered July 2026 in the middle of three simultaneous storylines: a scramble by Amazon and Walmart-owned Flipkart to muscle into 10-15 minute delivery, a wave of public-market listings led by Zepto’s imminent IPO, and a regulatory reckoning over dark-store food safety. Globally, the European Union closed its duty-free loophole on low-value parcels, directly hitting Shein, Temu and AliExpress. This update compiles verified developments reported and dated within July 2026, with the underlying data points and figures needed for planning and client conversations.

    1. Quick Commerce Remains India’s Fastest-Growing Retail Channel

    A report released by Equirus on July 7, 2026 confirmed that quick commerce will continue to outpace overall digital commerce growth through 2026, expanding at more than double the rate of the broader online retail market as operators keep pouring capital into dark-store networks and rapid-delivery infrastructure.

    India digital commerce market size (2026 est.): ₹8 lakh crore

    Quick commerce market size (2026 est.): ₹1.08 lakh crore, growing 40% YoY

    Combined dark stores — Blinkit + Instamart + Zepto (May 2026): 5,026 locations, up from 3,405 a year earlier

    Top seasonal growth categories: Ice cream, beverages, face-care products

    Emerging repeat-purchase categories: Personal care, beauty, electronics accessories, medicines, gifts, pet supplies

    Flagged risk factor: 46% rainfall deficit and potential food-inflation pressure on consumer demand

    Separately, Bain & Company’s outlook — cited widely in July coverage — projects India’s quick-commerce market will grow to $65-70 billion by 2030, contributing 45-50% of incremental e-retail gross merchandise value over the next five years, after roughly doubling annually over the past two years.

    • Equirus report via ANI News, July 7, 2026 — aninews.in

    • NewKerala, Quick Commerce Growth 2026 summary

    • Business Standard, “Why quick commerce has become a battle no retailer can afford to lose,” July 6, 2026

    2. Zepto’s IPO Moves Closer as the Top-Three Battle Intensifies

    Zepto is racing toward what would be the largest quick-commerce listing in Indian history. Having received SEBI’s formal observation-letter approval on May 8, 2026, the company filed an updated Draft Red Herring Prospectus (U-DRHP) on June 8, 2026, and multiple financial trackers reported through early July that Zepto is targeting a listing within the July-September 2026 quarter, though an exact date has not been announced.

    Fresh issue size: ₹8,010 crore

    Offer for sale (OFS): 11.35 crore equity shares from existing shareholders (Nexus Ventures, Contrary, Razor Ventures, Kaiser Permanente Group Trust and others)

    Total estimated issue size: ₹11,000-12,000 crore (~$1 billion)

    FY26 revenue from operations: ₹22,624 crore

    Average daily orders (FY26): 17.5 lakh

    Store count (as of March 31, 2026): 1,139 dark stores; 48 million users

    Lead bankers: Goldman Sachs, Morgan Stanley, JM Financial, Axis Capital, HSBC, IIFL Securities, Motilal Oswal

    The listing push comes as the competitive order in India’s quick-commerce top three continues to shift. Blinkit still leads on scale, processing 91.6 crore orders in FY26 (roughly 25 lakh orders a day) from a dark-store network of 2,243 stores as of March 31, 2026 — nearly double its closest rivals. Zepto overtook Swiggy Instamart on order volumes in the January-March FY26 quarter. Instamart itself posted FY26 revenue of ₹3,859 crore (up 81.2% YoY) but carried an adjusted EBITDA loss of ₹3,511 crore, trailing both peers on profitability. Together, Blinkit, Zepto and Instamart control roughly 85% of the quick-commerce market.

    • Kotak Neo, “Zepto Files Updated IPO Papers,” July 2026

    • Groww / IPO Central, Zepto SEBI approval coverage, May-July 2026

    • Upstox / Storyboard18, Zepto vs Blinkit vs Instamart operating-metrics comparison, 2026

    3. Amazon and Flipkart Go All-In on the “Minutes” War

    The most consequential shift in July 2026 is the entry of India’s two e-commerce giants into quick commerce at full scale. CNBC and Business Standard reported on July 2, 2026 that Amazon and Walmart-backed Flipkart are both accelerating delivery-in-minutes operations to defend their core online-retail base against Blinkit, Zepto and Instamart.

    Amazon’s new India investment: An additional $13 billion in AI and cloud infrastructure, taking total committed investment to $48 billion between 2026 and 2030

    Amazon’s quick-commerce ambition: To become the “largest delivery-in-minutes network” in India, with plans to expand to 300 cities

    Flipkart Minutes network: 1,000 micro-fulfillment centers built in under two years; targeting 1,500 centers by end-2026

    The escalation is playing out in real time through sale-season competition. Flipkart’s “Goat Sale” and Amazon’s own July sale event both launched on July 4, 2026, each offering 24 hours of early access to loyalty members (Flipkart Plus/Black) ahead of the general public — a direct contest for wallet share as quick-commerce blurs the line with traditional e-commerce shopping events.

    • CNBC, “Amazon, Walmart-owned Flipkart get ready to shake up India’s delivery-in-minutes sector,” July 2, 2026

    • Business Standard, “Amazon Now, Flipkart Minutes go full throttle in India’s qcom space,” July 2, 2026

    • TechCrunch, “Walmart-backed Flipkart expands quick-commerce push as Amazon ramps up in India,” June 23, 2026

    • The Tech Outlook / Desidime, Flipkart Goat Sale coverage, July 4, 2026

    4. Regulators Turn Up the Heat on Dark-Store Food Safety

    July brought the sharpest regulatory action yet on quick commerce’s dark-store model. On July 11, 2026, the Food Safety and Standards Authority of India (FSSAI) issued nine separate notices to Swiggy Instamart following consumer complaints of expired, spoiled and contaminated food being delivered through the platform. Days earlier, on July 4, 2026, FSSAI’s Northern Regional Office raided a food business operator in South-West Delhi, uncovering fraudulent re-labelling and unauthorized storage; more than 50,000 compromised food packs were seized and an FIR was registered.

    FSSAI notices to Swiggy Instamart: 9 notices issued July 11, 2026, citing FSS Act, 2006 violations

    Delhi enforcement raid: July 4, 2026 — over 50,000 food packs seized for fraudulent re-labelling and improper storage

    Regulatory direction: Government signalling a move toward risk-based dark-store inspection, with facilities that have poor compliance histories to be inspected more frequently

    Currently, dark stores are regulated under the same Food Safety and Standards (Licensing and Registration of Food Businesses) Regulations, 2011 that apply to conventional food businesses — there is no inspection checklist tailored to facilities processing thousands of rapid-fire orders daily. That gap is now central to the policy debate around India’s roughly 5,000-plus dark-store network.

    • Barristery, “FSSAI Issues Nine Notices to Swiggy Instamart,” July 2026

    • The News Mill / Lokmat Times, FSSAI Delhi raid coverage, July 4-5, 2026

    • Business Standard, “Who inspects India’s dark stores as quick commerce expands rapidly?,” June 25, 2026

    5. Retail Real Estate: Leasing Momentum Holds Through Q2

    On the brick-and-mortar side, Cushman & Wakefield’s Q2 2026 India retail report (published July 2026) showed continued strength in mall and high-street leasing despite a thin supply pipeline.

    Q2 2026 gross retail leasing (top 8 cities): 2.4 million sq ft — up 23.2% QoQ and 17.6% YoY

    H1 2026 total leasing: 4.35 million sq ft, up 3.1% over H1 2025

    Mall share of leasing: 51.3% (1.23 msf), up 33.4% QoQ and 21.9% YoY

    New Grade-A mall supply: Nil for a second consecutive quarter

    Strongest rental-growth corridors: Mumbai’s Linking Road (+22% YoY), Bengaluru’s Indiranagar 100 Feet Road (+12% YoY), Chennai’s Anna Nagar 2nd Avenue (+11% YoY), Ahmedabad’s CG Road (+11% YoY), Delhi NCR’s Khan Market (+9% YoY)

    Supply pipeline (2026-2028): ~12.7 msf, of which ~1.6 msf due in H2 2026 (Delhi NCR to account for over half)

    • Cushman & Wakefield, “India’s Retail Sector Growth in Q2 2026,” July 2026

    • Business Standard, “India’s Q2 2026 retail leasing grows 17.6% YoY,” July 1, 2026

    6. Walmart Fires the First Shot in a Summer Price War

    In the US, Walmart and Sam’s Club announced on July 6, 2026 that they are cutting prices across thousands of products — groceries, household essentials, toys and clothing — in a move analysts read as the opening salvo of a broader grocery price war. A Walmart representative indicated the rollback would run roughly 90 days, and industry watchers expect Kroger, Albertsons, Costco and Dollar Tree to respond with their own price investments through the second half of 2026. The move also lands as both Walmart and Target operate under new chief executives this year — John Furner at Walmart and Michael Fiddelke at Target — as the two chains jockey for position against Amazon.

    Price-cut announcement date: July 6, 2026

    Categories affected: Groceries, household essentials, toys, clothing

    Expected duration: ~90 days per rollback cycle

    • TheStreet / MarketWatch, Walmart price rollback coverage, July 2026

    • Review-Journal, “Walmart says it has cut prices on thousands of products,” July 2026

    • WWD, “Walmart & Target Name New CEOs: Retail Giants’ 2026 Outlook”

    7. EU Closes the Duty-Free Loophole on Shein, Temu and AliExpress

    The single biggest global e-commerce policy shift of the month: a flat €3 customs duty took effect across the European Union on July 1, 2026, ending years of tax-free entry for low-value parcels. The EU scrapped its long-standing exemption for parcels under €150 and replaced it with the flat per-item duty — a direct hit to the ultra-low-cost, high-volume model that Shein, Temu and AliExpress depend on for the European market.

    New duty: Flat €3 per parcel, effective July 1, 2026

    Previous exemption removed: Duty-free treatment for parcels valued under €150

    Early market impact: Temu’s ad visibility on Google Shopping has roughly halved; Shein is reported to be nearing a full exit from markets where border fees now apply

    For Indian D2C and export-oriented sellers watching the ultra-low-cost Chinese platforms, this is a live case study in how fast a favorable cross-border tax regime can close — and a reminder that landed-cost economics, not just price, will increasingly decide category winners in Europe.

    • Euronews, “EU slaps €3 duty fee on SHEIN, Temu and AliExpress imports,” July 1, 2026

    • Smarter Ecommerce, “Europe’s New Tariffs on Temu & Shein: What Google Shopping Data Reveals,” July 2026

    8. D2C Funding: Discipline Over Growth-at-All-Costs

    Coverage through July 2026 confirms the D2C funding environment has continued its multi-year shift away from growth-at-any-cost. Investors are now underwriting to a 3:1 LTV:CAC ratio, 40%+ gross margins and demonstrated cohort retention before committing capital, with 6-12 months of repeat-purchase data increasingly treated as a baseline requirement rather than a nice-to-have. Large-ticket consolidation continues to be led by strategic acquirers rather than venture rounds, as established CPG groups look to acquire data-rich, already-profitable D2C brands rather than fund unproven ones.

    Investor underwriting bar: 3:1 LTV:CAC minimum, 40%+ gross margin, proven cohort retention

    Diligence window now expected: 6-12 months of verified repeat-purchase data

    Dominant M&A pattern: Strategic/corporate acquirers over pure venture rounds for later-stage D2C brands

    • Tenten.co, “Ecommerce Funding Landscape 2026: What Investors Want from D2C Brands”

    • Ellty, “D2C Investors: 45 Active VCs Funding Consumer Brands 2026”

    Bottom Line for Retail, D2C and Quick-Commerce Operators

    Three threads matter most heading into August 2026. First, the delivery-speed war has stopped being a quick-commerce-only fight — Amazon and Flipkart’s move into minutes-delivery will pressure Blinkit, Zepto and Instamart on cost per order well before Zepto’s IPO prices. Second, dark-store compliance is no longer a background risk; with FSSAI actively issuing notices and conducting raids in July, operators without audit-ready SOPs and traceability are exposed. Third, the EU’s parcel-duty change is a preview of how quickly a favorable trade regime can be unwound — a useful data point for any D2C brand building an export or cross-border strategy on thin-margin, high-volume assumptions.

    — End of July 2026 update —

    Gaurang Govind