Category: Quick Commerce

  • Quick Commerce Is No Longer About 10-Minute Delivery — It Is Becoming a New Retail Format

    Quick Commerce Is No Longer About 10-Minute Delivery — It Is Becoming a New Retail Format

    When quick commerce started gaining traction in India, the big attraction was simple: get your order in 10 minutes.

    Milk, bread, eggs, snacks, cold drinks, fruits and vegetables — things people needed quickly could suddenly reach their homes without a trip to the neighbourhood store.

    For a while, the entire conversation was about speed.

    Who can deliver faster?

    10 minutes or 15 minutes?

    But I think we are now looking at something much bigger.

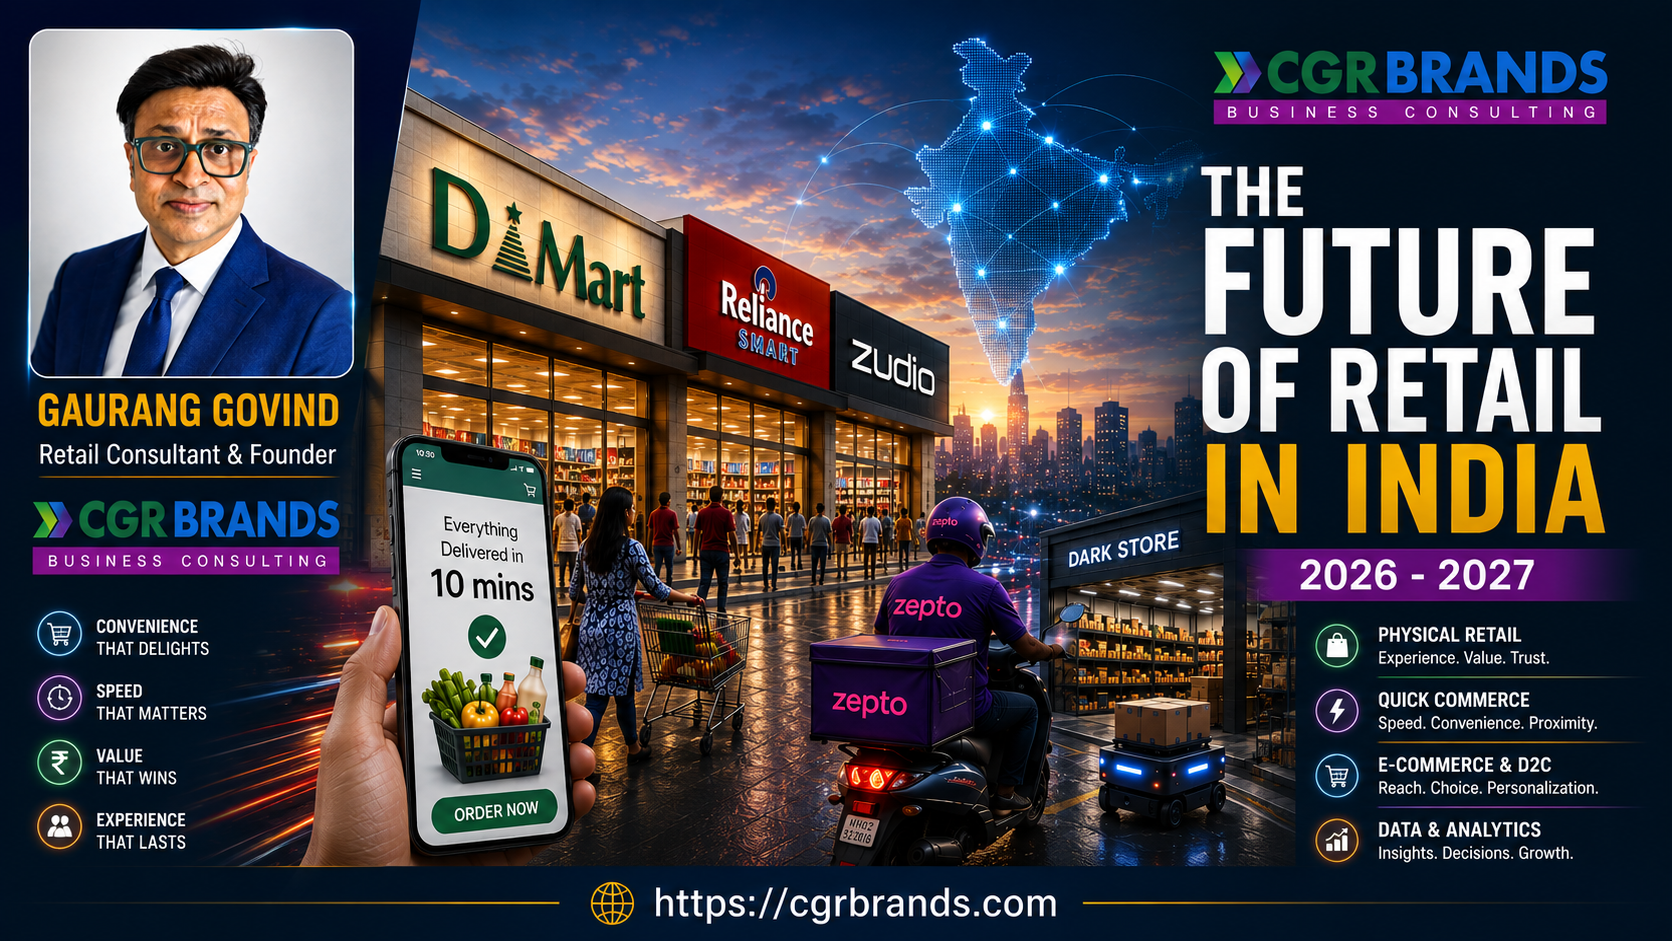
    Quick commerce is slowly becoming a new retail format.

    The reason is quite simple. These platforms are no longer trying to solve only an urgent shopping need. They are trying to become part of the customer’s regular shopping behaviour.

    Think about how people actually shop.

    They don’t always wake up thinking, “Today I will visit a grocery store.”

    They think, “We are out of milk.”

    “I need snacks for tonight.”

    “I forgot toothpaste.”

    “Guests are coming.”

    “I need a small gift.”

    These are shopping missions.

    Quick commerce is trying to capture these missions one by one.

    And that changes the game.

    The first generation of quick commerce was largely about groceries and everyday essentials. Today, the assortment is moving into many other categories — beauty, personal care, electronics, gifting, home products and more.

    Once the customer starts buying these categories regularly, the platform is no longer just delivering products.

    It is competing for the customer's basket.

    That is where I believe traditional retailers need to pay attention.

    Because the biggest change is not happening in delivery.

    It is happening in inventory.

    A 10-minute delivery promise sounds impressive to the customer. But behind that promise sits a much more complicated operation.

    The product has to be available close to the customer.

    The forecast has to be reasonably accurate.

    The right quantity has to be stocked.

    The order has to be picked quickly.

    The product has to be packed correctly.

    And someone still has to deliver it profitably.

    If the retailer keeps too little stock, the customer sees “out of stock.”

    Keep too much stock and the business starts carrying unnecessary working capital. Products age. Discounts increase. Fresh products get damaged. Wastage goes up.

    This becomes particularly important in fruits and vegetables and other perishables.

    A retailer cannot solve an availability problem simply by putting more stock into a dark store.

    The quality of the forecast matters.

    This is something I have seen repeatedly in retail. Inventory problems are often treated as a technology problem. In reality, the technology can only work as well as the demand data, processes and discipline behind it.

    That is why I think the next competitive battle in quick commerce will not simply be about who delivers in 10 minutes.

    It will be about who can maintain better availability without carrying excessive inventory.

    That is a very different game.

    Traditional retailers already understand many parts of this equation.

    They have spent decades managing assortment, inventory, margins, store productivity, shrinkage, wastage and working capital.

    What is changing is the operating model.

    A traditional store waits for the customer to walk in.

    A dark store waits for the order to come through the app.

    The traditional store uses shelves to present products.

    The quick-commerce platform uses the app to present products.

    The traditional retailer measures sales per square foot.

    The quick-commerce operator needs to think about sales, orders and contribution from each fulfilment location.

    The customer sees a simple app screen.

    Behind that screen is a fairly complex retail operation.

    And this is where I think the conversation around quick commerce needs to become more mature.

    Sales growth alone is not enough.

    Quick Commerce Retailers need to ask harder questions.

    What is the inventory turn?

    What percentage of orders get fulfilled completely?

    How often does the customer find the product unavailable?

    What does picking cost?

    What does delivery cost?

    How much inventory gets damaged?

    How much money is tied up in local inventory?

    And perhaps the most important question:

    Are customers coming back because the platform is genuinely useful, or only because someone is subsidising the order?

    These questions will become increasingly important as the sector matures.

    There is another change that I find particularly interesting.

    The traditional argument used to be:

    Online versus offline.

    I don’t think that is the right argument anymore.

    A physical store can also become a digital fulfilment point.

    A customer can walk into the store and buy something.

    Another customer, sitting two kilometres away, can order from the same inventory.

    The same store can therefore serve both customers.

    This changes the role of the store.

    It can become a place for shopping, product discovery, experience, fulfilment and local inventory — all at the same time.

    So, rather than asking whether quick commerce will replace traditional retail, I would ask a different question:

    How quickly will traditional retailers learn to operate with the same level of convenience? and How efficiently QUick Commerce companies can run like a Retailer to ensure backend excellence and inventory availability at optimium costs

    Because the customer has already changed.

    Once someone gets used to receiving a product within minutes, asking that customer to wait two days for a basic product can feel very different.

    Convenience changes expectations.

    And expectations eventually change retail.

    I don’t think the future of quick commerce will be decided by the fastest delivery time.

    The 10-minute promise helped create the market.

    But speed alone won’t build a sustainable retail business.

    The winners will need to get several things right at the same time:

    Right product. Right location. Right inventory. Right price. Right availability. Right cost.

    That is retail.

    Quick commerce has simply put that retail equation on a much smaller clock.

    And perhaps that is the real story.

    Quick commerce started by promising to deliver faster.

    It is now trying to change the way we shop.

    The next phase will tell us whether it can also change the economics of retail.

  • What 5,200 Customer Reviews Reveal About Process Failures in Quick Commerce

    What 5,200 Customer Reviews Reveal About Process Failures in Quick Commerce

    What Customer Complaints Can Tell Us About Quick Commerce Operations
    A customer complaint rarely starts where the customer experiences it.
    A late delivery may not be a delivery problem.
    A delayed refund may not be a customer-support problem.
    A cancelled order may not be a cancellation problem.
    And that is exactly where many organisations get improvement wrong.
    They respond to the visible complaint instead of investigating the process that created it.
    Quick commerce makes this challenge even more interesting.
    The customer sees a simple promise: fast, convenient and reliable delivery.
    Behind that promise, however, sits a complex chain of inventory, store operations, picking, packing, technology, rider allocation, delivery, payments, refunds and customer support.
    When that chain breaks, the customer does not see the process.
    They see the outcome. And they complain about it.
    That makes customer complaints far more than customer-service data.
    They can be early signals of process variation, waste and defects.
    With that perspective, we analysed customer reviews across five major quick-commerce platforms to understand what recurring complaints could tell us about the underlying customer journey.
    The Objective
    The purpose was not to rank companies or identify winners and losers.
    Instead, we wanted to answer three questions:

    What are customers complaining about most frequently?
    What patterns emerge when all complaints are analysed together?
    Which recurring problems may require a structured Lean Six Sigma investigation?

    The study analysed 5,200 recent customer reviews across the five platforms.
    Of these, 1,401 reviews—or 26.9%—contained identifiable complaints.
    The remaining reviews were positive or did not contain a clearly identifiable complaint.
    In other words, roughly one in every four reviews contained a signal that something in the customer journey had not worked as expected.

    What Did the Combined Data Reveal?
    When all five platforms were analysed together, complaints were not concentrated around one single operational problem.
    The major themes included:

    Refund and customer-support issues
    General dissatisfaction
    Unclassified complaints
    Delivery delays
    Product quality issues
    Missing or incorrect items
    Pricing and charge-related concerns
    Order cancellations
    Trust-related concerns
    Technical and app-related problems

    One finding stood out immediately.
    A significant number of complaints were broad, emotional or difficult to classify into one specific defect.
    When a customer says, “Worst experience”, the dissatisfaction is clear. The root cause is not.
    Was the problem delivery?
    Was it the product?
    Was it the refund?
    Was it customer support?
    Or did several process failures combine to create one poor experience?
    This is where complaint analysis alone reaches its limit.
    It can tell us where customers feel the pain.
    It cannot always tell us why the process created it.

    The Pattern Was Not the Same for Every Company
    The most interesting insight was not simply the overall number of complaints.
    It was how differently the complaint patterns appeared across the platforms.
    One platform showed a significantly higher complaint rate, with concerns concentrated around:

    Refunds
    Customer support
    Product quality

    Another showed a stronger delivery-related pattern.
    Another had relatively greater concerns around pricing and charges.
    Another showed a combination of delivery delays and order cancellations.
    This distinction matters.
    These companies operate in the same industry and compete for similar customers.
    But the customer-facing defects are not identical.
    That means a generic “customer experience improvement programme” may be too broad to solve the real problem.
    Each complaint pattern points towards a different part of the process that needs investigation.

    Company Comparison

    Article content


    What Does This Mean from a Lean Six Sigma Perspective?
    The data does not tell us what solution each company should implement.
    And it should not.
    Jumping directly from a complaint to a solution is one of the most common mistakes in improvement work.
    A late delivery does not automatically mean more riders are required.
    A refund delay does not automatically mean more customer-service employees are needed.
    A cancellation does not automatically mean inventory is the problem.
    The visible complaint is the symptom.
    The real question is:
    Where did the process begin to fail?
    Based on the patterns identified in this study, organisations may need structured Lean Six Sigma projects around five broad areas.
    1. Refund and Customer Support
    Key questions include:

    Where does waiting occur?
    Why do some cases take longer to resolve?
    Why are repeat customer interactions required?
    Where do handoffs and escalations create variation?

    2. Delivery Reliability
    The customer sees a late delivery.
    The investigation needs to trace the entire journey:
    Order → Picking → Packing → Rider Allocation → Dispatch → Delivery
    The critical question is:
    At which point did the variation enter the process?
    3. Product and Order Quality
    For missing, incorrect, damaged or poor-quality items:

    Where did the defect originate?
    Inventory?
    Picking?
    Packing?
    Storage?
    Delivery?

    4. Order Cancellations
    A cancellation is often the final visible outcome of an earlier failure.
    The investigation needs to understand what happened before the order reached that point.
    5. Pricing, Transparency and Trust
    Some complaints may reflect an operational defect.
    Others may reflect a gap between:
    What the customer expected and What the process delivered or communicated.
    Both require investigation.

    The Bigger Lesson
    The strongest takeaway from this study is simple:
    Customer complaints are process signals.
    A customer sees the final failure.
    The organisation needs to trace that failure backwards.
    A delivery complaint may have started long before dispatch.
    A refund complaint may have nothing to do with the person speaking to the customer.
    A missing product may have entered the process before the order was packed.
    That is why these findings should not immediately lead to solutions.
    They should lead to better questions.

    Why are refunds delayed?
    Why do customers need repeated support interactions?
    Why does delivery performance vary?
    Why do orders get cancelled?
    Why do incorrect or damaged products reach customers?
    Why do customers perceive some charges or transactions as unclear?

    These are not simply customer-service questions.
    They are process questions.
    And process questions require structured root-cause investigation.

    The Way Forward
    This study is a starting point, not a diagnosis.
    It identifies where customers experience recurring problems.
    The next step is to investigate why those problems occur.
    That is where Lean Six Sigma can provide a structured path:
    Customer Complaint → Problem Definition → Measurement → Root-Cause Analysis → Improvement
    The biggest mistake would be to assume that the visible complaint is also the root cause.
    It rarely is.
    Quick commerce will continue to compete on speed.
    But the next competitive advantage may not come from delivering a few minutes faster.
    It may come from something much harder to build:
    A process that works consistently—even when things do not go as planned.
    Comments

    Comments settings


    Photo of Gaurang Govind

    Like

    Comment

    Sharerce

  • India Retail 2024–2027: From Store Expansion to Intelligent Retail Expansion I A retail case study on what changed, what is coming next, and what ret

    India Retail 2024–2027: From Store Expansion to Intelligent Retail Expansion I A retail case study on what changed, what is coming next, and what ret

    The Hook

    India’s retail expansion story is entering its next phase.

    The question is no longer:

    “How many stores can we open?”

    The question is:

    “How intelligently can we expand while protecting productivity, profitability and customer relevance?”

    Post banner

    Between 2024 and 2026, India’s leading retailers significantly increased their physical footprints while quick commerce simultaneously created a completely different retail proposition: availability at the doorstep within minutes.

    Now the real battle is moving towards Tier 2, Tier 3 and emerging consumption centres.

    And I believe the next two years will be less about the race for store count and more about the race for better retail economics.

    What happened between 2024 and 2026?

    Three examples illustrate the direction.

    Reliance Retail

    Reliance Retail increased its store network from 19,340 stores in FY2025 to 20,160 stores in FY2026, while gross revenue increased from ₹3.31 lakh crore to approximately ₹3.71 lakh crore. Its Smart Bazaar network crossed 1,000 stores, with a significant part of that network serving Tier 2 and smaller markets.

    More importantly, Reliance is combining physical stores, digital commerce and hyperlocal commerce rather than treating them as separate businesses.

    Trent’s Zudio

    Zudio reached 963 stores across 313 cities by FY2026, compared with 765 stores in FY2025 and 545 stores in FY2024. The company’s own reporting highlights accessibility, sharp price points, in-house merchandise and rapid expansion as key elements of the model.

    Avenue Supermarts

    Avenue Supermarts, the operator of the DMart chain, moved from 365 stores in FY2024 to 415 in FY2025 and 500 in FY2026.

    The FY2026 expansion is particularly interesting: 85 stores were added, including 45 stores in Tier 2+ markets, while the company entered 39 new cities, 34 of them Tier 2+. It also entered Uttar Pradesh, Haryana, Odisha, Uttarakhand and Goa.

    The message from these examples is clear:

    India’s organised retail opportunity is moving deeper into the country. This we all know.

    But there is another force changing the game.

    The Quick-Commerce Challenge

    Quick commerce has changed the consumer’s definition of convenience.

    The customer no longer thinks:

    “I need to visit a store.”

    The customer increasingly thinks:

    “I need it now.”

    Blinkit, Swiggy Instamart and Zepto have built large dark-store networks, while Amazon and Flipkart are now increasing their investments in rapid delivery.

    In June 2026, Reuters reported that Amazon planned to expand its rapid-delivery service to 300 Indian cities, while Flipkart was targeting approximately 1,500 quick-commerce locations.

    This creates an interesting future scenario.

    Traditional retailers will increasingly have stores.

    Quick-commerce companies will increasingly have dark stores.

    E-commerce companies will increasingly combine warehouses, marketplaces and rapid fulfilment.

    The consumer will simply choose whichever channel delivers the best combination of:

    Price + availability + speed + trust + assortment + experience.

    My Forecast for 2026–2027

    1. Tier 2 and Tier 3 will become the primary expansion laboratory

    I expect retailers to become more aggressive in smaller cities—but also more selective.

    The next phase will not be:

    “Let’s enter every Tier 2 city.”

    It will be:

    “Let’s identify the right micro-markets inside the right Tier 2 cities.”

    Population alone will not be sufficient.

    Retailers will increasingly evaluate:

    – Catchment population

    – Household income

    – Consumer spending

    – Competition

    – Footfall potential

    – Real-estate cost

    – Logistics cost

    – Delivery density

    – Digital adoption

    – Category potential

    – Store productivity potential

    This means location analytics will become a board-level expansion capability.

    —

    2. Cluster expansion will become more important than isolated expansion

    The next winning model may not be one store in 20 cities.

    It may be five to ten stores in one carefully selected cluster.

    Why?

    Because clustering can improve:

    Supply-chain efficiency → inventory availability → marketing efficiency → management supervision → brand awareness → customer familiarity.

    Retailers should therefore stop measuring expansion only by the number of stores opened.

    They should measure:

    Revenue per cluster.

    Profit per cluster.

    Inventory turns per cluster.

    Supply-chain cost per cluster.

    Customer acquisition cost per cluster.

    This is where retail analytics can transform expansion decisions.

    —

    3. Quick commerce will not kill physical retail—but it will change its role

    This is perhaps the most important prediction.

    Physical stores will increasingly need to answer:

    “Why should the customer visit me?”

    For grocery, the answer could be:

    Better value + larger assortment + monthly shopping + fresh produce + discovery.

    For fashion:

    Trial + experience + instant gratification + newness.

    For electronics:

    Demonstration + advice + service + installation.

    For lifestyle:

    Discovery + experience + social shopping.

    The physical store therefore needs to become more than a transaction point.

    It needs to become a customer-experience and fulfilment asset.

    —

    4. Dark stores will face an operational-quality test

    There is another issue that I believe deserves far greater attention.

    A dark store is still a retail operation.

    Technology can manage orders.

    Technology can generate inventory alerts.

    Technology can optimise delivery routes.

    But people still have to manage:

    Expiry → FEFO → hygiene → temperature → receiving → storage → pest control → picking → product handling.

    Recent food-safety enforcement in Maharashtra illustrates the risk. Authorities inspected quick-commerce establishments and suspended permits at 12 warehouses after identifying issues including cockroach infestations, rodent droppings and other sanitation problems.

    This should not be viewed only as a quick-commerce problem.

    It is an industry-wide retail operations lesson.

    As the network expands, retailers need stronger:

    Retail audits + SOP compliance + training + accountability + store-level ownership.

    —

    5. E-commerce and direct-to-consumer brands will push deeper into smaller cities

    This is another major structural change.

    Smaller-city consumers are not waiting for physical stores.

    They are discovering brands online.

    According to Unicommerce data reported by the India Brand Equity Foundation, Tier 2 and Tier 3 cities were expected to contribute around 66% of new direct-to-consumer orders in FY2026.

    This changes the expansion equation.

    A brand can now enter a city digitally before opening a physical store.

    That creates an important consulting opportunity:

    Digital-first → Data validation → Pilot store → Cluster expansion

    Instead of:

    Store first → Hope for demand → Correct later

    This can significantly reduce expansion risk.

    —

    What should retailers do now?

    Action 1: Build a micro-market expansion model

    Don’t approve a new store only because the city looks attractive.

    Create a scoring model covering:

    Demand + competition + rent + catchment + logistics + digital demand + store economics.

    —

    Action 2: Establish a 12–24 month store maturity dashboard

    Every new store should be tracked against:

    Sales per sq. ft./ GMROF

    Gross margin.

    GMROI.

    Inventory turns.

    Inventory cycle

    Conversion.

    Average basket value.

    Shrinkage.

    Manpower productivity.

    Contribution margin.

    This allows management to distinguish between a temporary maturity issue and a fundamentally weak location.

    —

    Action 3: Design the store and dark store together

    The future will increasingly require omnichannel operating models.

    A physical store may serve:

    Walk-in customers + online orders + click-and-collect + local fulfilment.

    Retailers should therefore redesign:

    Inventory → picking → replenishment → manpower → technology → customer journey

    as one integrated process.

    —

    Action 4: Create independent operational audits- audits are crucial specially third party remove bias

    Expansion multiplies risk.

    Every additional location creates another opportunity for:

    Expiry leakage + shrinkage + poor hygiene + inventory inaccuracies + SOP deviation + manpower inefficiency.

    Retailers should therefore create a structured audit framework covering:

    People + Process + Product + Place + Technology + Compliance.

    —

    Action 5: Treat Tier 2 and Tier 3 as different markets—not smaller metros

    This is critical.

    Consumers in smaller cities may have different:

    Price sensitivities, pack-size preferences, fashion choices, shopping missions, credit behaviour and local brand preferences.

    Retailers should analyse local behaviour before standardising the assortment.

    —

    The Biggest Prediction for 2027

    I believe the retail industry will gradually move from:

    “Expansion at scale”

    to

    “Intelligent expansion at scale.”

    The winners will not necessarily have the largest number of stores.

    They will have the best store economics, supply chain, data systems, customer understanding and execution discipline.

    The next competitive advantage will come from connecting:

    Physical retail + e-commerce + direct-to-consumer + quick commerce + data + supply chain.

    And this will create a new retail equation:

    Right Market × Right Format × Right Assortment × Right Inventory × Right Execution = Profitable Growth

    —

    Final Recap

    The last two years proved that physical retail is not disappearing.

    It is changing.

    Reliance Retail has crossed 20,000 stores.

    Zudio has reached nearly 1,000 stores.

    Avenue Supermarts has reached 500 stores and is pushing deeper into Tier 2+ markets.

    At the same time, quick commerce and e-commerce are moving rapidly into smaller markets.

    So the next two years will not be about choosing between stores and digital.

    They will be about building the right combination.

    For retailers, my recommendation is straightforward:

    Analyse before expanding.

    Pilot before multiplying.

    Cluster before spreading.

    Measure productivity before celebrating footprint.

    Audit operations before scaling.

    And most importantly:

    Build the organisation’s capability at the same speed as you build its footprint.

    Because in the next phase of Indian retail, opening the store may be easy. Running 500 or 5,000 stores consistently will be the real competitive advantage.

    Sources and further reading

    – “Reliance Industries — FY2025–26 Retail Business Overview” (https://reference-url-citation.invalid/7)

    – “Reliance Industries — FY2025–26 Integrated Annual Report” (https://reference-url-citation.invalid/8)

    – “Trent Limited — FY2025–26 Integrated Annual Report” (https://reference-url-citation.invalid/9)

    – “Trent Limited — Annual Reports and Company Filings” (https://reference-url-citation.invalid/10)

    – “Avenue Supermarts — FY2024–25 Annual Report” (https://reference-url-citation.invalid/11)

    – “Motilal Oswal — Avenue Supermarts FY2026 expansion analysis” (https://reference-url-citation.invalid/12)

    – “Reuters — Amazon and Flipkart quick-commerce expansion” (https://reference-url-citation.invalid/13)

    – “Reuters — Food-safety enforcement at quick-commerce warehouses” (https://reference-url-citation.invalid/14)

    – “India Brand Equity Foundation — Tier 2/3 direct-to-consumer growth” (https://reference-url-citation.invalid/15)

    #RetailIndia #RetailStrategy #RetailExpansion #RetailOperations #QuickCommerce #DarkStores #Ecommerce #DirectToConsumer #Tier2Cities #Tier3Cities #OmnichannelRetail #RetailAnalytics #SupplyChain #StoreProductivity #FMCG #RetailConsulting #CustomerExperience #InventoryManagement #GMROI

    Gaurang Govind

    Business Consulting firm